
Indiana's Silver Tsunami - Why Local Business Owners Need a Succession Plan Before They Need One
 Drive down almost any Main Street in Indiana and you will see the same story repeated: a hardware store, a machine shop, a family restaurant, a trucking company — all built over twenty, thirty, even forty years by an owner who is now closer to retirement than to the day they opened the doors. Multiply that story by tens of thousands of businesses across the state, and you have what economists and demographers have started calling the "Silver Tsunami": a wave of business owners reaching retirement age all at roughly the same time, with far fewer of them having a real plan for what comes next.
This is not a distant, someday problem. It is already underway, and it is already reshaping local economies.
The Real Threat Isn't Competition
Ask a business owner what keeps them up at night, and you will usually hear about competitors, labor costs, supply chains, or interest rates. Rarely do you hear about succession. Yet for many communities, the single greatest economic threat over the next decade will not come from a rival company opening across town. It will come from good businesses closing simply because no one was ready to take them forward.
Research on small business ownership in Indiana and across the Midwest consistently points to the same conclusion: a substantial share of business owners are approaching an age where retirement, health issues, or simple fatigue will force a transition - and most have not documented, funded, or even discussed a plan for that transition with anyone.
The Silver Tsunami Ripple Effect
When an owner exits without a plan, the effects rarely stay contained to one balance sheet. Without an effective plan in place, the owner may lose meaningful value – value they earned with hard work, value meant to fund retirement, inheritances, and charitable donations. The loss from a failure to plan does not stop there. Employees lose jobs or are absorbed into a hurried, undervalued sale. Customers lose a trusted vendor. Suppliers lose a customer. Landlords lose a tenant. Communities lose tax base and, often, a piece of their identity. A business that could have transitioned smoothly to a family member, a management team, or a well-matched buyer instead closes its doors, liquidates its assets, or sells at a discount to whoever happens to be available at the moment the owner can no longer keep going.
None of this is inevitable. It is simply what happens by default when planning is delayed or absent.
Preparation Is Preservation
 The good news is that none of these outcomes are required. An owner who begins planning three, five, seven, or ten years ahead of an eventual exit has real choices: who the business transfers to, on what timeline, at what value, and under what terms. An owner who waits until circumstances force a business transition or sale typically has far fewer options and far less leverage.
That is the idea behind this series, Exiting on Your Terms. Over the coming articles, we will walk through the questions that matter most - what your business is really worth, how to position the business to maximize its fair market value, how to keep deal proceeds instead of losing them to avoidable tax and structuring mistakes, how to treat family members fairly, and how to prepare for a sale before a buyer ever shows up at the table.
Where to Start
The starting point is not a spreadsheet or a listing agreement. It is a single, honest question: if you had to leave your business today — for any reason — what would happen to it, to your employees, and to your family? If you are not confident in the answer, that uncertainty is the real risk, and it is entirely fixable with enough runway.
The businesses that survive this transition period will overwhelmingly be the ones whose owners started planning before they had to. Contact a member of the Barrett McNagny Business Succession Planning team today.
Contact Our Team:
About the Authors:
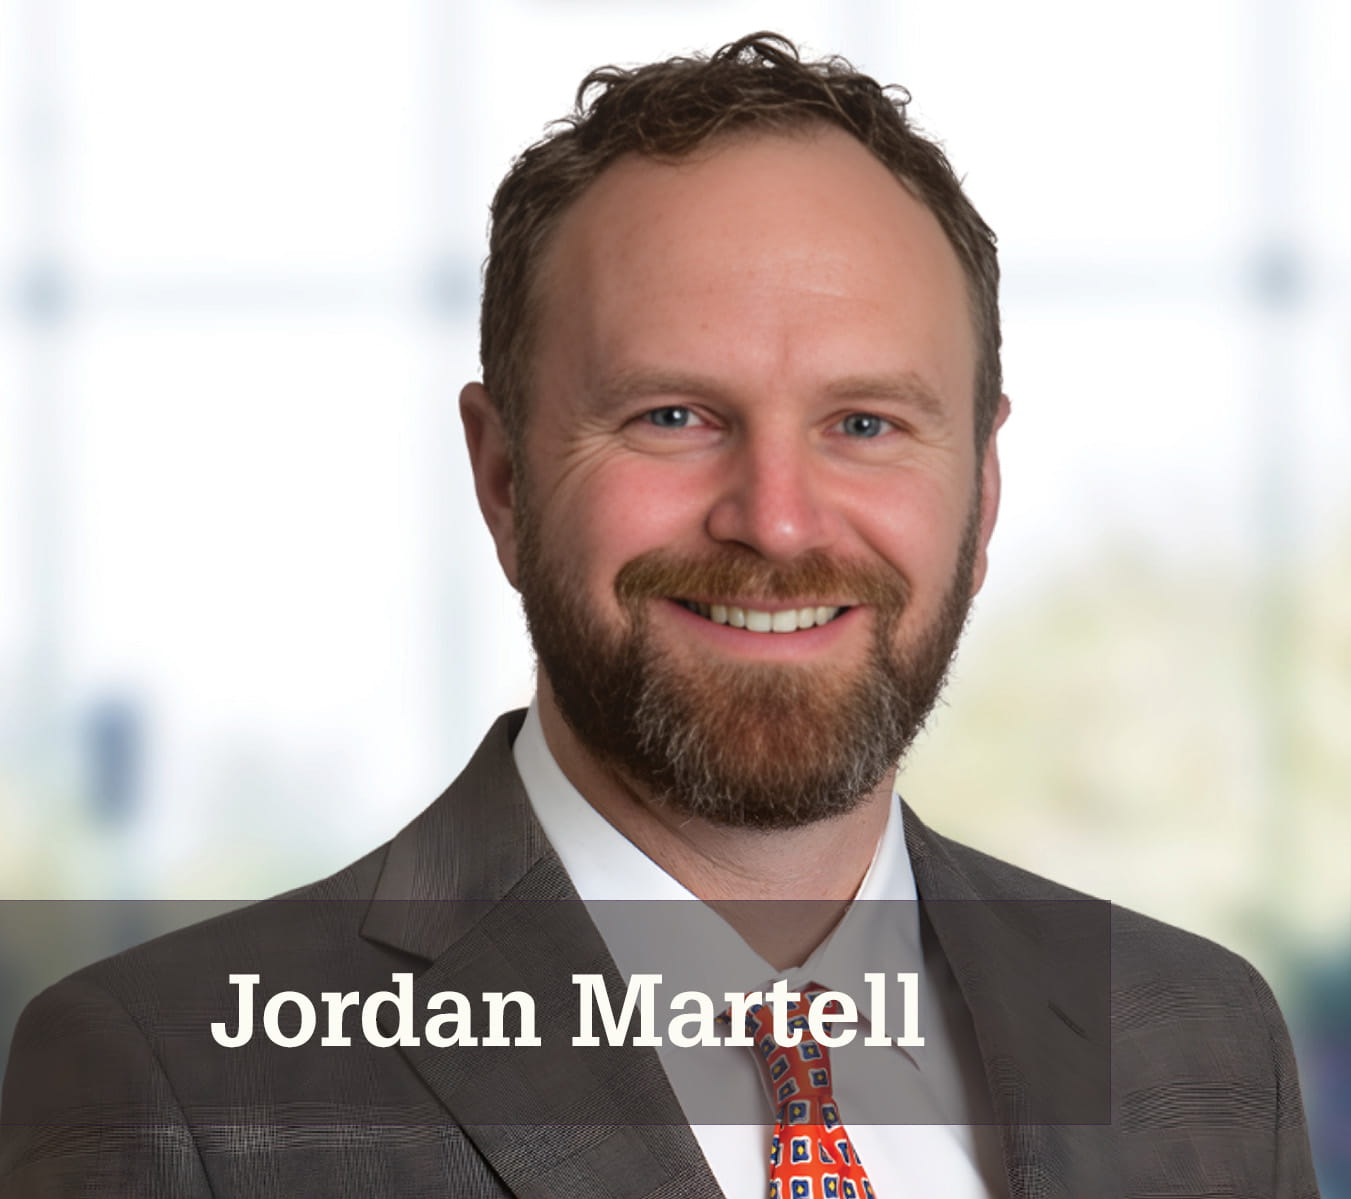
Jordan Martell is a business savvy attorney with a mission to support institutions that are the backbone of thriving communities: local employers and businesses. He believes strong local economies built strong, resilient communities.
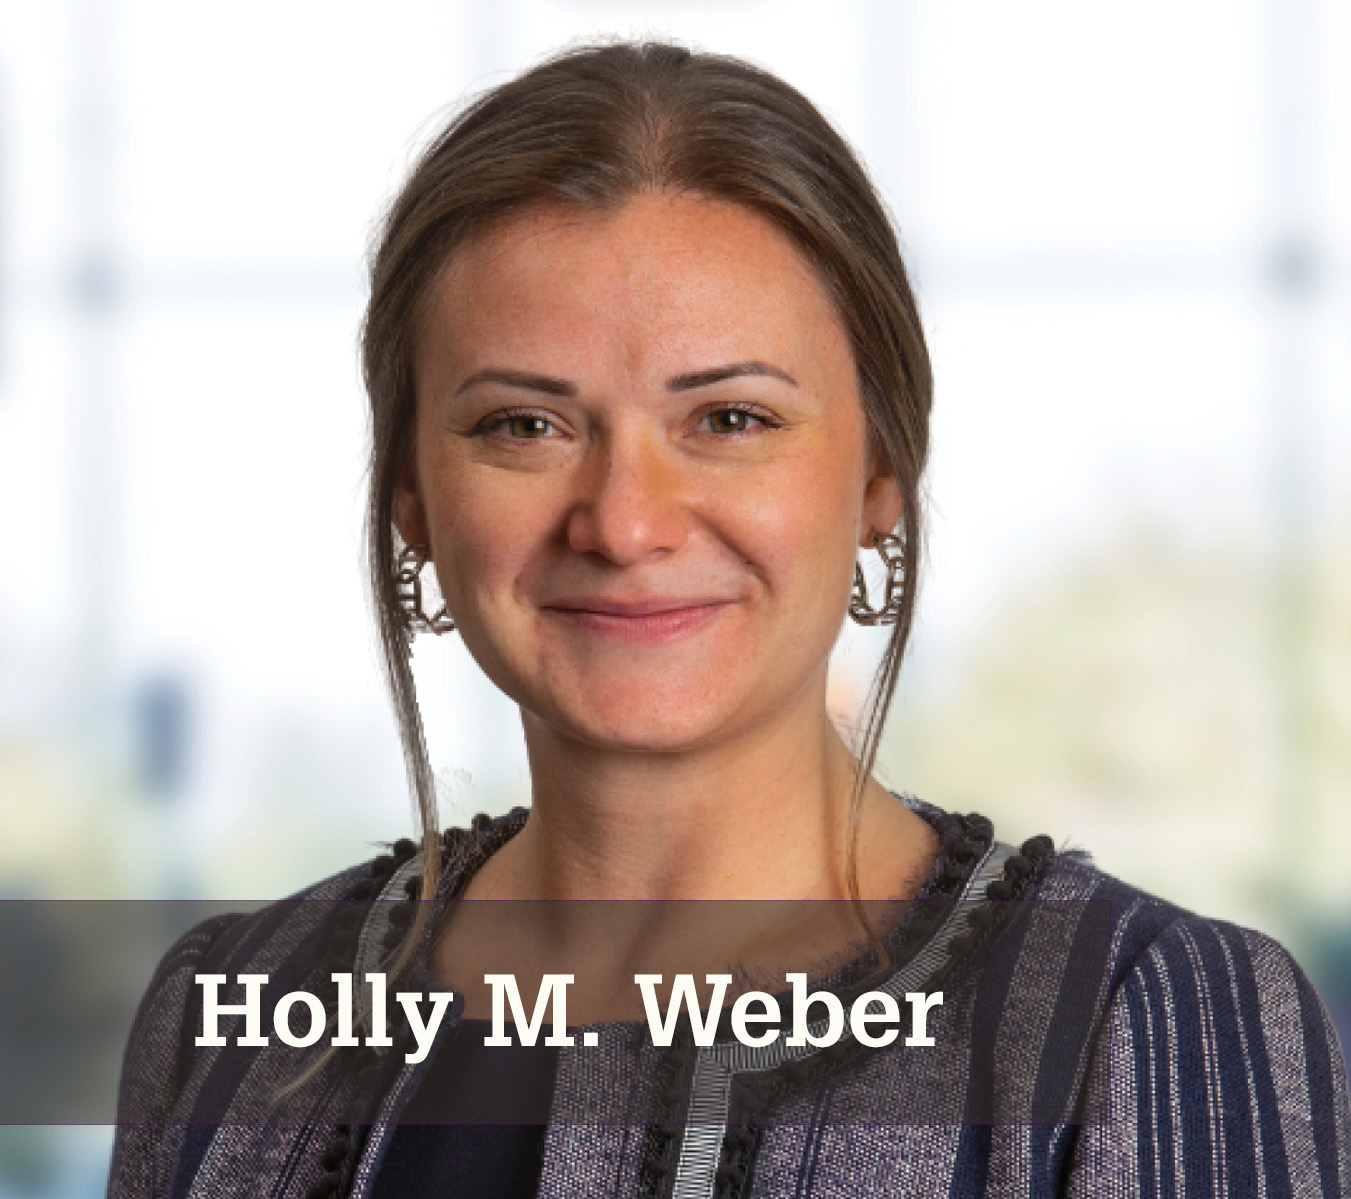
Holly M. Weber is an experienced attorney who specializes in helping people plan for ownership transitions, business sales, and long-term succession. She works with closely held and family-owned companies to address the legal, tax, family, and practical issues that can determine whether a transition succeeds or stalls. Holly’s goal is to help owners protect what they have built and exit on their own terms, whether through a sale, family succession, management transition, or other planned exit.
If you are wondering where your own business stands, contact us at (260) 423-9551 to schedule a confidential Business Succession Readiness Conversation today.